2026 Quarter 2: Sales Tax Rate Tools

Notification from Washington Department of Revenue:

Sales Tax Rate Tools
The Quarter 2, 2026, Washington State sales tax rate changes are now available.

On April 1, 2026, the sales tax rate lookup tool, including the map and latitude/longitude search, will include the following changes:

  • Sales and use tax within the City of Asotin will increase one-tenth (.001) of one percent for emergency communication systems and facilities.
  • Sales and use tax within the City of Battle Ground will increase three-tenths (.003) of one percent for housing and related services, and local law enforcement programs.
  • Sales and use tax within the City of Burlington will increase two-tenths (.002) of one percent for local law enforcement programs.
  • Sales and use tax within the City of Centralia will increase two-tenths (.002) of one percent for transportation services.
  • Sales and use tax within Clark County will increase two-tenths (.002) of one percent for housing and related services, and local law enforcement programs.
  • Sales and use tax within the City of Edmonds will increase one-tenth (.001) of one percent for transportation services.
  • Sales and use tax for lodging businesses within the City of Enumclaw will increase three-tenths (.003) of one percent for transportation services and decrease three-tenths (.003) of one percent for Special hotel-motel tax. This is a reporting change only and not a rate change.
  • Sales and use tax within the City of Goldendale will increase one-tenth (.001) of one percent for criminal justice purposes, fire protection purposes, or both.
  • Sales and use tax within Jefferson County will increase three-tenths (.003) of one percent for local law enforcement programs, and transportation services, except for the City of Port Townsend which will increase one-tenth (.001) of one percent for local law enforcement programs.
  • Sales and use tax within the City of Kalama will increase one-tenth (.001) of one percent for transportation services.
  • Sales and use tax for lodging businesses within King County will increase for transportation services and decrease for Special hotel-motel tax while others will increase by three-tenths (.003) of one percent for transportation services.
  • Sales and use tax within the City of Lynnwood will increase one-tenth (.001) of one percent for local law enforcement programs.
  • Sales and use tax within the City of Richland will increase one-tenth (.001) of one percent for transportation services.
  • Sales and use tax within the City of Ritzville will increase one-tenth (.001) of one percent for transportation services.
  • Sales and use tax within Skagit County will increase one-tenth (.001) of one percent for local law enforcement programs.
  • Sales and use tax within the City of Tacoma will increase one-tenth (.001) of one percent for local law enforcement programs.
  • Sales and use tax within the City of Toppenish will increase one-tenth (.001) of one percent for local law enforcement programs.
  • Sales and use tax within the City of Tukwila will increase one-tenth (.001) of one percent for local law enforcement programs.
  • Sales and use tax within the City of Washougal will increase three-tenths (.003) of one percent for housing and related services, and local law enforcement programs.
  • Sales and use tax within the City of Wenatchee will increase one-tenth (.001) of one percent for local law enforcement programs.
  • Sales and use tax within the City of Winthrop will increase one-tenth (.001) of one percent for transportation services.
  • Sales and use tax within the City of Woodway will increase one-tenth (.001) of one percent for transportation services. A new lodging code has been created, this is a reporting change only.

Preparing for 2025 Tax Filing: Essential Tips and Key Tax Updates

Happy Holidays from Alisa Na CPAs and Advisors!

As 2026 approaches, we would like to share several timely reminders for our individual and business clients. The Internal Revenue Service is encouraging taxpayers to take proactive steps now to prepare for filing 2025 federal income tax returns next year. With year-end approaching, there are practical actions you can take to streamline the filing process and avoid last-minute surprises as the 2026 tax season begins.

Theย One Big Beautiful Bill Act (OBBBA)ย introduces multiple changes and new provisions that may affect federal taxes, credits, and deductions. Key updates include modifications related to tips, overtime pay, car loan interest, senior taxpayers, and the permanent extension of several provisions that were previously scheduled to expire on December 31, 2025.

Gather and Organize 2025 Tax Documents
To make tax time easier, establish an adequate record-keeping system, either electronic or paper, to organize all essential documents in one place. This includes year-end income forms such as:

  • Forms W-2 from employers
  • Forms 1099 from banks or other payers
  • Forms 1099-K from third-party payment networks
  • Forms 1099-NEC for non-employee compensation
  • Forms 1099-MISC for miscellaneous income
  • Forms 1099-INT for interest income
  • Records of all digital asset transactions

Having complete documentation helps ensure an accurate return and can reduce processing delays or refund issues.

IRS Online Account
Individuals can create or access IRS Online Accounts for both individual and business purposes.
IRS Online Account for Individuals
IRS Business Tax Account

With an IRS Online Account, you can:

  • View, make, and cancel payments
  • Set up or change payment plans and check your balance
  • View key details from your most recent tax return, such as adjusted gross income
  • Request anย Identity Protection PIN
  • Obtain account transcripts, including wage and income records
  • Sign tax forms such as powers of attorney or tax information authorization

Deadline for Final 2025 Estimated Tax Payment – January 15, 2026
Taxpayers who receive non-wage incomeโ€”such as self-employment earnings, annuity payments, unemployment compensation, or income from digital assetsโ€”may need to make estimated or additional tax payments.

Wage earners can use theย IRS Tax Withholding Estimatorย on IRS.gov to determine whether additional withholding is needed and help avoid an unexpected balance due when filing.

If you make estimated tax payments and qualify for any new deductions, you may want to review whether your final estimated payment should be adjusted. Similarly, wage earners should consider whether their current withholding remains appropriate.

Digital Assets and Taxes in 2025 โ€“ Form 1099-DA

The IRS has finalized new cryptocurrency reporting rules beginning with the 2025 tax year. If you buy, sell, or trade crypto through a custodial digital asset broker (such as Coinbase, Kraken, Binance, or a custodial wallet provider), these platforms will be required to report certain taxable transactions to the IRS usingย Form 1099-DA.
Form 1099-DA will include your information, the digital asset and amount sold, the sale date, and gross proceeds. The first 2025 forms are expected to be issued byย March 31, 2026.
Please note:ย for the 2025 tax year, Form 1099-DA willย notย include cost basis. You will still need to track and calculate your basis before your return can be filed. Beginning in 2026, brokers will also be required to report cost basis.
Information onย how to report digital asset transactions, including calculating capital gain or loss, determining basis, and reporting the income on the correct form, can also be found on theย digital assetsย landing page.

Refund Timing and How to Avoid Delays

Most IRS refunds are issued within 21 days; however, you should not rely on receiving your 2025 federal refund by a specific date. Some returns take longer if the IRS needs to review them for errors, missing information, or possible identity theft or fraud.
Under the PATH Act, the IRS cannot release refunds for returns claiming theย Earned Income Tax Credit (EITC)ย or theย Additional Child Tax Credit (ACTC)ย until mid-February.

IRS Moves Toward All-Electronic Refunds
The IRS has announced it will largely stop issuing paper refund checks, with limited exceptions. Taxpayers will be required to receive refunds electronically.
Filing electronically and selecting direct depositย remains the fastest and safest way to receive your refund.ย Please provide your tax preparer with updated bank account informationย to avoid delays.

One Big Beautiful Bill Act (OBBBA):
Key Federal Tax Changes Affecting Individuals

Senior Tax Deduction
For tax years 2025 through 2028, taxpayers age 65 or older may qualify for an additionalย $6,000ย deduction per person, or $12,000 if both spouses qualify. The deduction phases out for income over $75,000 (single) or $150,000 (married filing jointly).

No Tax on Tips
Qualified cash tips received in eligible occupations may be deductible up toย $25,000ย annually. The deduction phases out for income over $150,000 (single) or $300,000 (married filing jointly).

No Tax on Overtime
Qualified overtime compensation may be deductible up toย $12,500ย ($25,000 for married filing jointly), subject to the same income phase-out thresholds as tips. This applies to overtime required under the Fair Labor Standards Act that exceeds your regular rate of pay.

Trump Accounts (New Child Savings Accounts)
A new savings account for children, similar to a traditional IRA. Parents may begin contributing on July 4, 2026. For children born between January 1, 2025, and December 31, 2028, the government may provide a one-time $1,000 deposit, provided both the child and parent have valid Social Security numbers.

Car Loan Interest Deduction
Through 2028, you may deduct up toย $10,000ย of interest on loans for qualifying passenger vehicles purchased after December 31, 2024. The deduction phases out for income over $100,000 (single) or $200,000 (married filing jointly). The vehicle must be new, manufactured primarily for public road use, and final assembly must occur in the United States.

State and Local Tax (SALT) Deduction
The SALT deduction cap increases toย $40,000ย for 2025 and $40,400 for 2026, with 1% annual increases through 2029, then reverting to $10,000 in 2030. The enhanced deduction phases out for taxpayers with income over $500,000 ($250,000 for married filing separately).

Green Energy Credits
Many residential and vehicle clean energy credits expanded under the Inflation Reduction Act are reduced or eliminated after 2025, including the Clean Vehicle (EV) Credit for purchases afterย September 30, 2025.

  • Theย Clean Vehicle Creditย (EV tax credit) was terminated for purchases after September 30, 2025. Existing credits claimed before the sunset remain valid.
  • Credits for residential energyย efficiency upgrades, such as heat pumps, windows, and insulation, are reduced or eliminated after 2025.
  • The bill blocks future extensions of green credits without separate legislation, so Congress would have to pass a new law to revive these incentives later.

Enhanced Child Tax Credit
The Child Tax Credit increases toย $2,200ย per qualifying child for 2025 and with inflation adjustments beginning in 2026. The refundable portion is $1,700. Income limits of thanย $200,000 for a single return & $400,000 if filing a joint returnย apply, and Under newย OBBBA SSN requirements, at least one parent/taxpayer must have a work-eligible SSN (not an ITIN), and the child must also have a SSN.

IRS Gift Tax Exclusion
The annual IRS gift tax exclusion isย $19,000ย per recipient for both 2025 and 2026. Gifts above this amount must be reported on a federal gift tax return.

Federal Lifetime Gift and Estate Tax
For 2025, the federal lifetime gift, estate, and GST tax exemption amount isย $13.99 millionย per individual. While the 2025 lifetime estate and gift tax exemption remains $13.99 million per person, the One Big Beautiful Bill Act provides relief starting January 1, 2026. The exemption will permanently increase to $15 million per person (indexed for inflation), eliminating the previously scheduled reduction to approximately $7 million. This change provides much greater certainty for long-term estate planning strategies.

Educator Credit
You can deduct up toย $300ย of unreimbursed classroom expenses if you are an eligible educator. If both spouses are educators and file jointly, they can deduct up to $600 (with each capped at $300).

Estimated Tax Payments
The IRS underpayment and late-payment interest rate for individual taxpayers will beย 7%ย in 2025. Please consider making estimated payments by April 15, even if you request an extension to file your tax return.
Rules to avoid an estimated tax penalty have not changed:

  • Pay 100% of prior year tax (or 110% if AGI is over $150,000)
  • For the four quarters of 2025, the estimated tax penalty rate is 7%
  • If you qualify for new OBBBA deductions, we recommend reviewing whether a 4th quarter federal estimate is still needed

Social Security Updates
Social Security benefits will increase by 2.8% beginning inย 2026. Social Security wage base will increase to $184,500 inย 2026. For individuals under full retirement age (67), the earned income limit increases to $24,480 in 2026.

IRS Business Mileage Rate
Theย IRS standard mileage rates areย 70 centsย per mile for business purposes in 2025.
Standard mileage rates | Internal Revenue Service

Retirement, HSA, and RMD Planning
Maximum Retirement Contributions for 2025
Contribute the maximum allowable amount to retirement accounts such as 401(k)s, IRAs, or SEP IRAs. These contributions can reduce your taxable income and enhance your retirement savings.

  • Traditional IRA or Roth IRA:ย $7,000 ($8,000 if age 50 or older). This limit is unchanged from 2024.
  • SIMPLE IRA:ย $16,500 ($20,000 if age 50 or older).
  • 401(k) elective deferrals:ย $23,500 for individuals under age 50.
  • Catch-up contributionย for thoseย 50 or older:ย $7,500 (total $31,000).
  • Some age bands (ages 60โ€“63) may have a higher catch-up limit of $11,250 for 401(k) and $5,250 for SIMPLE under SECURE 2.0 provisions.
  • SEP IRA:ย Contributions are limited to the lesser of 25% of compensation orย $70,000.

Required Minimum Distributions (RMDs)
Required Minimum Distributions (RMDs) are mandatory, taxable withdrawals from IRAs and retirement plans that generally begin atย age 73. The first RMD is due by April 1 of the year after you turn 73, with all future RMDs required by December 31 each year, potentially resulting in two taxable distributions in the first RMD year.ย For example, if you turned 73 in 2025, your first RMD is due by April 1, 2026, and your second RMD (for 2026) is due by December 31, 2026.

Maximum Health Savings Account (HSA) Contribution Limits for 2025

  • Self-only coverage:ย $4,300.
  • Family coverage:ย $8,550
  • Those 55 and older can contribute an additional $1,000 as a catch-up contribution.

2026 Tax Year โ€“ Charitable Giving
Beginning in 2026, OBBBA permits non-itemizers to claim an above-the-line deduction for cash contributions to public charities, up to $1,000 for single filers and $2,000 for married filing jointly, without using Schedule A.
Also, if you plan to make charitable contributions, consider donating appreciated assets (such as stocks or real estate) to potentially enhance your tax benefits while avoiding capital gains on the donated property. Be sure to keep thorough documentation for all contributions.

Washington State Tax Updates

Washington Long-Term Capital Gains Tax
Beginning in tax year 2025, Washingtonโ€™s long-term capital gains tax applies at:

  • 7% on the first $1 million of taxable Washington capital gains
  • 9.9% (7% + 2.9%) on gains exceeding $1 million

Washington Capital Gains Standard Deduction
The Washington capital gains standard deduction for 2025 isย $278,000, up from $270,000 in 2024. This amount is adjusted annually for inflation.

Please contact us in February if you would like to schedule a consultation regarding Washington capital gains planning. For additional details, visit theย Washington Department of Revenue website.

These guidelines are intended to support year-end tax planning. Because every financial situation is unique, we recommend scheduling a meeting so we can review your specific circumstances and identify the most effective strategies.

Thank you for trusting us with your financial needs. We look forward to supporting your financial goals in the coming year. Please do not hesitate to reach out with any questions.

Sincerely,
Alisa Na CPAs & Advisors

Related services from Alisa Na CPAs & Advisors

2026 Minimum Wage Resources

2026 Minimum Wage Resources

Washington State: https://www.lni.wa.gov/news-events/article/25-27

The Washington State Department of Labor & Industries (L&I) announced an increase in the stateโ€™s minimum wage to $17.13 per hour, effective on January 1, 2026.

Seattle: https://www.seattle.gov/laborstandards/ordinances/minimum-wage?utm_medium=email&utm_source=govdelivery

Starting January 1, 2026, all employers, regardless of schedule size, will be required to pay the same minimum wage of $21.30 per hour. Small employers will no longer be able to count tips and/or payments toward an employeeโ€™s medical benefit plan toward an employee’s minimum compensation requirements under Seattleโ€™s Minimum Wage Ordinance.

Bellingham: https://cob.org/services/business/city-minimum-wage

The city minimum wage will be set at $2.00 ($19.13) above the applicable Washington State minimum wage, effective on January 1 every year. The city will establish the city minimum wage within two weeks of the publication of the new state minimum wage.

Burien: https://www.burienwa.gov/city_hall/laws_regulations/minimum_wage

Please visit the City of Burien website for latest minimum wage requirements.

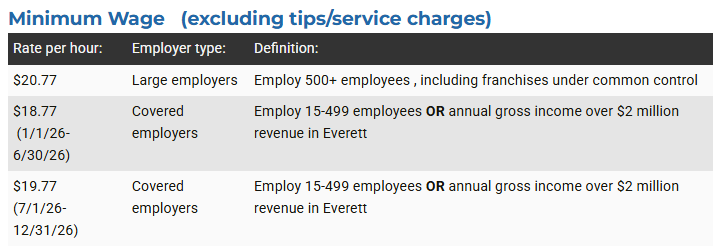
Everett: https://www.everettwa.gov/3287/Minimum-wage

Employers who do not meet the covered status below will need to meet the WA state minimum wage.

King County (unincorporated areas): https://kingcounty.gov/en/dept/local-services/governance-leadership/local-government-for-unincorporated-king-county/minimum-wage

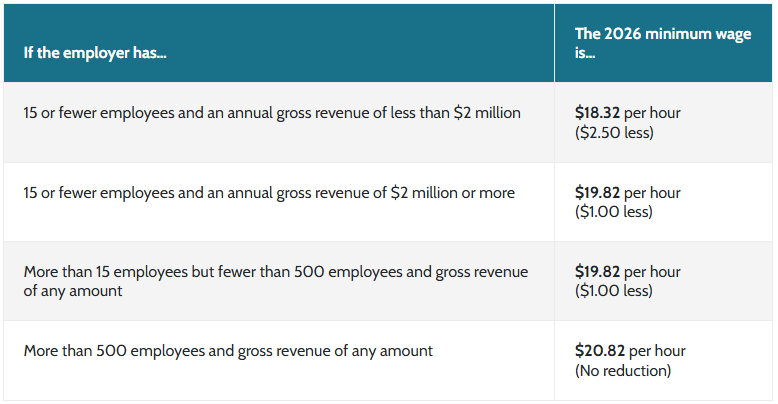
As of January 1, 2026, the minimum hourly wage in unincorporated King County will be $20.82. There will be three temporary exceptions, based on business size and gross revenue.

Renton: https://www.rentonwa.gov/city_hall/finance/2024_labor_standards

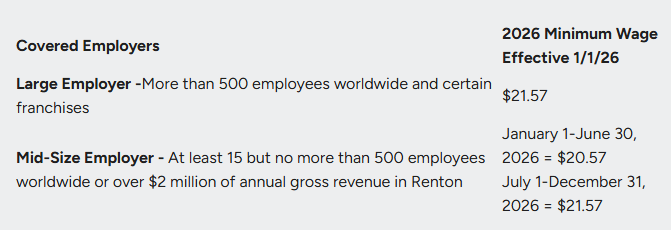
Covered employers will be required to pay a new higher minimum wage for hours worked in the City. Covered employers are required to pay employees not less than the minimum hourly wage as follows:

Employers that do not fall within the Large or Mid-Size Employer described above are not covered by the new minimum wage rates but must continue to meet the State of Washington minimum wage requirements.

SeaTac: https://www.seatacwa.gov/home/showpublisheddocument/40154/638954226601570000

2026 Minimum Wage: $20.74 per hour

The increase in the living wage rate (2.81%) has been calculated using the consumer price index for urban wage earners and clerical workers, (CPIW) for the twelve (12) months prior to September 1 as calculated by the United States Department of Labor. Therefore, in accordance with SeaTac Municipal Code (SMC) Section 7.45.050, the living wage rate in effect for hospitality and transportation employees within the City will increase to $20.74, effective January 1, 2026.

Tukwila: https://www.tukwilawa.gov/departments/finance/minimum-wage-and-fair-access-to-additional-hours-of-work/

Effective January 1st, 2026, Tukwila Minimum Wage hourly rates will be $21.65.


Important Washington State Sales Tax Changes Affecting Your Business

The Washington State Legislature has passed Engrossed Substitute Senate Bill (ESSB) 5814, which introduces significant changes to the state’s sales tax laws. These changes, which will take effect on October 1, 2025, are aimed at modernizing the tax code. It is important for all business owners to understand how these new rules may impact their operations.

This article provides a summary of the key changes based on interim guidance from the Washington Department of Revenue.

Digital Automated Services (DAS) and the Definition of a “Retail Sale”

ESSB 5814 broadens the scope of services subject to retail sales tax and the retailing Business and Occupation (B&O) tax. Here are the key takeaways:

  • Data Processing is Now a Retail Service: Services such as data processing will now be considered a retail service and will be subject to retail sales tax.
  • Expanded Taxation of Digital Services: Previously, certain digital services were exempt from sales tax. This law removes those exemptions. Now, services such as digital advertising, data processing, live-streamed presentations, and services that involve significant human effort are all considered taxable retail sales.
  • New Exclusion for Telehealth: A new DAS exclusion has been created for telehealth and telemedicine services.
  • Affiliate Sales Exclusion: Certain sales between members of an affiliated group are now excluded from the definition of a retail sale.
  • Clarification on Professional Services: The legislature has clarified that professional services will not become taxable simply because they are delivered electronically. The Department of Revenue has provided a framework to distinguish between professional services subject to the service and other B&O tax and taxable DAS.
  • Sourcing DAS Sales: The new law outlines a clear hierarchy for determining the location of a DAS sale for tax purposes.

Learn more: https://dor.wa.gov/laws-rules/interim_guidance_statements/interim-guidance-statement-regarding-changes-made-essb-5814-das-exclusions-and-definition-retail

New Tax Treatment for Custom Software

The new law also changes how custom software is taxed. Hereโ€™s what you need to know:

  • Custom Software as a Retail Sale: The sale of “custom software” and the “customization of prewritten software” will now be considered a retail sale. This means these sales will be subject to both retailing B&O tax and retail sales tax.
  • Previous Tax Classification: Previously, these sales were taxed under the service and other activities B&O tax classification.
  • Key Definitions:
    • Custom Software: Software created for a single person.
    • Customization of Prewritten Computer Software: An alteration or modification of prewritten software for a specific person.
  • Sourcing Custom Software Sales: The sale of custom software is generally taxed based on the location where the purchaser receives the service.
  • Multiple Points of Use (MPU) Exemption: Businesses that license custom or customized software for use in multiple states may be eligible for the MPU exemption. This allows the purchaser to apportion and pay use tax directly to the Department of Revenue instead of paying retail sales tax at the time of purchase. However, the MPU exemption is not available for bundled transactions.

Learn More: https://dor.wa.gov/laws-rules/interim_guidance_statements/interim-guidance-statement-regarding-changes-made-essb-5814-custom-software

What This Means for Your Business

The changes introduced by ESSB 5814 are complex and could have a significant impact on your business’s tax obligations. It is crucial to review your sales of services and software to determine how these new rules will affect you.

Please note that the information above is based on interim guidance from the Department of Revenue. The Department will be issuing final guidance in the future.

We encourage you to contact us to discuss your specific situation and ensure you are prepared for these changes when they take effect on October 1, 2025.

Related services from Alisa Na CPAs & Advisors

Federal Refund Checks End Sept 30, 2025: How to Switch to Electronic IRS Payments

The U.S. Department of the Treasury has announced that, starting September 30, 2025, the federal government will stop issuing paper checks for most federal paymentsโ€”including IRS tax refunds. The change is part of a broader initiative to improve security, reduce fraud and theft, and speed up payment delivery by transitioning to electronic methods.

At the same time, federal agenciesโ€”including the IRSโ€”are moving incoming payments (what taxpayers send to the government) to electronic processing โ€œas soon as practicable.โ€ Treasuryโ€™s implementation guidance instructs agencies to phase out lockbox processing and adopt digital collection solutions. While that signals paper checks for tax payments are being phased down, a single, IRSโ€‘specific cutoff date for mailed check payments has not been posted as of today.


Key takeaways

  • Refunds: The IRS will no longer mail paper refund checks in the ordinary course for payments issued on or after Sept 30, 2025 (limited exceptions apply โ€œto the extent permitted by lawโ€). Plan now for direct deposit or another approved electronic refund option.
  • Paying the IRS: Agencies are directed to process all receipts electronically as soon as practicable and eliminate lockboxes, which means paper checks for tax payments are being phased out. Move to electronic payment methods now to avoid disruption.
  • What to use: Recommended options include IRS Direct Pay, EFTPS, and debit/credit card or digital wallet via IRSโ€‘approved processors (fees may apply; cards arenโ€™t for payroll tax deposits).


Whatโ€™s changing for IRS refunds

Beginning September 30, 2025, federal disbursements will be electronic by default. For the IRS, that means no routine paper refund checks after that date. Exceptions will be limited and grounded in law and Treasury guidance. Electronic delivery is faster and significantly reduces the risk of mail theft and check fraud.

Direct deposit is the fastest way to receive your refund. Donโ€™t have a traditional bank account? Some mobile apps and reloadable prepaid debit cards support direct deposit when they provide routing and account numbersโ€”check with your provider to confirm.


Whatโ€™s changing for payments to the IRS

The March 25 Executive Order directs the government to move all federal payments and collections to electronic methods, and Treasuryโ€™s implementation guidance tells agencies to eliminate lockboxes and process all receipts electronically โ€œas soon as practicable.โ€ For taxpayers, this means a continuing shift away from mailing checks to pay balances due or estimated taxes. Transition now, even though the IRS has not published a single hard cutoff date for accepting mailed checks as of this writing.


Your electronic options (and when to use them)

1) IRS Direct Pay (ACH from your bank account)

Best for individuals paying 1040โ€‘series balances, extensions, or estimates. No fees; schedule each payment as needed.

Learn more: https://www.irs.gov/payments/direct-pay

2) EFTPS โ€” Electronic Federal Tax Payment System

Ideal for businesses (and individuals who want scheduling, history, and recurring payments).

Plan ahead: after you enroll online, your PIN typically arrives by U.S. mail in about 5โ€“7 business days before you can activate and pay.

Enroll: https://www.eftps.gov/eftps

3) Debit/credit card or digital wallet (IRSโ€‘approved processors)

Convenient for oneโ€‘off payments; processing fees apply.

Note: You cannot pay federal payroll tax deposits by cardโ€”use EFTPS for those.

Options: https://www.irs.gov/payments/pay-your-taxes-by-debit-or-credit-card


If you receive federal benefits by paper check

This policy change covers most federal disbursements. If you still get a paper check for Social Security, VA, or other benefits, switch to direct deposit or, if eligible, a Treasuryโ€‘sponsored Direct Expressยฎ card using the options Treasury lists.

Enroll at GoDirect: https://www.godirect.gov/

Or call Treasuryโ€™s Electronic Payment Solution Center: 800โ€‘967โ€‘6857 (Monโ€“Fri, 9:00 a.m.โ€“7:00 p.m. ET).

Always verify requests to change your payment method to avoid scams.


FAQ

Will the IRS still accept mailed paper checks after September 30, 2025?

Treasuryโ€™s guidance requires agencies to process all receipts electronically โ€œas soon as practicableโ€ and to phase out lockboxes, but it doesnโ€™t set a single nationwide cutoff date for mailed checks to the IRS. The direction is clear: move to electronic payments now to avoid disruption.

What are my options if I donโ€™t use a traditional bank account?

Some mobile apps and reloadable prepaid debit cards accept direct deposit if they provide routing and account numbers. Confirm with your provider before filing.

How long does EFTPS enrollment take?

After you enroll online, your PIN typically arrives by U.S. mail within about 5โ€“7 business days. Youโ€™ll then activate and set your online password before making payments.

Why is the government ending most paper checks?

To fight fraud and theft, reduce costs, and speed up payments. The Executive Order mandates modernizing payments to and from the federal government, and Treasury is implementing it across agencies.

Are there any exceptions to electronic refunds or payments?

Yes, the policy allows limited exceptions โ€œto the extent permitted by law.โ€ Treasury will publish exception processes where needed.


We can help you switchโ€”today

Our team will help you choose the right electronic method for refunds and payments, enroll you in EFTPS if needed, and set up direct deposit accurately.

Contact us to get started now and avoid lastโ€‘minute scrambling.

Related services from Alisa Na CPAs & Advisors

9์›” 30์ผ๋ถ€๋กœ ํ™˜๊ธ‰ ์ˆ˜ํ‘œ ์ข…๋ฃŒ: IRS ์ „์ž ํ™˜๊ธ‰/๋‚ฉ๋ถ€ ์ „ํ™˜

IRS ๋ฐœํ‘œ์— ๋”ฐ๋ผ ์˜ค๋Š” 2025๋…„ 9์›” 30์ผ๋ถ€ํ„ฐ ์—ฐ๋ฐฉ ์ •๋ถ€๋Š” ํ™˜๊ธ‰์„ ํฌํ•จํ•œ ๋Œ€๋ถ€๋ถ„์˜ ์ง€๊ธ‰์„ ๋” ์ด์ƒ ์ข…์ด ์ˆ˜ํ‘œ๋กœ ๋ฐœํ–‰ํ•˜์ง€ ์•Š์Šต๋‹ˆ๋‹ค. ์ด๋ฒˆ ์กฐ์น˜๋Š” ์šฐํŽธ ์ ˆ๋„์™€ ์ˆ˜ํ‘œ ์‚ฌ๊ธฐ ์œ„ํ—˜์„ ์ค„์ด๊ณ , ์ฒ˜๋ฆฌ ์†๋„๋ฅผ ๋†’์ด๋ฉฐ, ์ง€๊ธ‰ ์ง€์—ฐ์„ ์ตœ์†Œํ™”ํ•˜๊ธฐ ์œ„ํ•œ ๊ฒƒ์ž…๋‹ˆ๋‹ค.

๋˜ํ•œ, ์„ธ๊ธˆ ๋‚ฉ๋ถ€ ๋ฐฉ์‹ ์—ญ์‹œ ์ „์žํ™”๋กœ ์ „ํ™˜๋˜๊ณ  ์žˆ์Šต๋‹ˆ๋‹ค. ์žฌ๋ฌด๋ถ€๋Š” ๊ฐ ๊ธฐ๊ด€์— ๊ฐ€๋Šฅํ•œ ํ•œ ๋น ๋ฅด๊ฒŒ ์ „์ž ๋‚ฉ๋ถ€ ์ฒด๊ณ„๋ฅผ ๋„์ž…ํ•˜๊ณ , ๊ธฐ์กด์˜ ์šฐํŽธ ์ˆ˜ํ‘œ ์ฒ˜๋ฆฌ ์‹œ์Šคํ…œ(๋ฝ๋ฐ•์Šค)์„ ๋‹จ๊ณ„์ ์œผ๋กœ ์—†์• ๋„๋ก ์ง€์นจ์„ ๋‚ด๋ ธ์Šต๋‹ˆ๋‹ค. ๋‹ค๋งŒ, IRS๊ฐ€ ์–ธ์ œ๋ถ€ํ„ฐ ์šฐํŽธ ์ˆ˜ํ‘œ ๋‚ฉ๋ถ€๋ฅผ ์™„์ „ํžˆ ์ค‘๋‹จํ• ์ง€์— ๋Œ€ํ•œ ๊ตฌ์ฒด์ ์ธ ๋‚ ์งœ๋Š” ์•„์ง ๋ฐœํ‘œ๋˜์ง€ ์•Š์•˜์Šต๋‹ˆ๋‹ค. ๋ฐฉํ–ฅ์€ ์ด๋ฏธ ์ •ํ•ด์ ธ ์žˆ์œผ๋‹ˆ ์ง€๊ธˆ๋ถ€ํ„ฐ ์ „์ž ๋ฐฉ์‹์œผ๋กœ ์ค€๋น„ํ•ด ๋‘์‹œ๋Š” ๊ฒƒ์ด ์•ˆ์ „ํ•ฉ๋‹ˆ๋‹ค.

ํ•ต์‹ฌ ์ •๋ฆฌ

  • ํ™˜๊ธ‰: 2025๋…„ 9์›” 30์ผ ์ดํ›„ ๋ฐœํ–‰๋˜๋Š” ํ™˜๊ธ‰์€ ์›์น™์ ์œผ๋กœ ์ „์ž ์ง€๊ธ‰(์ง์ ‘ ์ž…๊ธˆ ๋“ฑ)์œผ๋กœ ์ด๋ค„์ง‘๋‹ˆ๋‹ค. ๋ฒ•๋ น์ด ํ—ˆ์šฉํ•˜๋Š” ์ผ๋ถ€ ์˜ˆ์™ธ๋Š” ๋‚จ์•„ ์žˆ์Šต๋‹ˆ๋‹ค.

  • ๋‚ฉ๋ถ€: ์žฌ๋ฌด๋ถ€ ์ง€์นจ์— ๋”ฐ๋ผ ๋ชจ๋“  ๊ธฐ๊ด€์ด ์ „์ž ๋‚ฉ๋ถ€๋กœ ์ „ํ™˜ ์ค‘์ด๋ฉฐ, ์šฐํŽธ ์ˆ˜ํ‘œ ์ฒ˜๋ฆฌ๋Š” ๋‹จ๊ณ„์ ์œผ๋กœ ํ์ง€๋ฉ๋‹ˆ๋‹ค. ์ง€๊ธˆ ๋ฐ”๋กœ ์ „์ž ๋‚ฉ๋ถ€ ๋ฐฉ์‹์œผ๋กœ ๋ฐ”๊พธ์‹œ๋Š” ๊ฒŒ ์ข‹์Šต๋‹ˆ๋‹ค.

  • ๋‚ฉ๋ถ€ ๋ฐฉ๋ฒ•: IRS Direct Pay(๊ณ„์ขŒ์ด์ฒด/ACH), EFTPS(์ „์ž ์—ฐ๋ฐฉ ์„ธ๊ธˆ ๋‚ฉ๋ถ€ ์‹œ์Šคํ…œ), ์‹ ์šฉยท์ง๋ถˆ์นด๋“œ/๋””์ง€ํ„ธ ์ง€๊ฐ‘(์ˆ˜์ˆ˜๋ฃŒ ๋ฐœ์ƒ ๊ฐ€๋Šฅ). ๋‹จ, ๊ธ‰์—ฌ ์›์ฒœ์ง•์ˆ˜ ์˜ˆ์น˜(Federal Tax Deposit)๋Š” ๋ฐ˜๋“œ์‹œ EFTPS๋ฅผ ์‚ฌ์šฉํ•ด์•ผ ํ•ฉ๋‹ˆ๋‹ค.

IRS ํ™˜๊ธ‰์€ ์–ด๋–ป๊ฒŒ ๋‹ฌ๋ผ์ง€๋‚˜?

2025๋…„ 9์›” 30์ผ๋ถ€ํ„ฐ๋Š” ์—ฐ๋ฐฉ ํ™˜๊ธ‰๊ธˆ ์ง€๊ธ‰์ด ์ „์ž ์ง€๊ธ‰์œผ๋กœ ์ „ํ™˜๋ฉ๋‹ˆ๋‹ค. ๋”ฐ๋ผ์„œ ๊ธฐ์กด์ฒ˜๋Ÿผ ์šฐํŽธ์œผ๋กœ ์ข…์ด ์ˆ˜ํ‘œ๋ฅผ ๋ฐ›๋Š” ์ผ์€ ์‚ฌ์‹ค์ƒ ์‚ฌ๋ผ์ง‘๋‹ˆ๋‹ค(๋ฒ•์  ์˜ˆ์™ธ ์กด์žฌ). ์ „์ž ์ง€๊ธ‰์€ ์ง€๊ธ‰ ์†๋„๊ฐ€ ํ›จ์”ฌ ๋น ๋ฅด๊ณ , ๋ถ„์‹ค์ด๋‚˜ ์ ˆ๋„ ์œ„ํ—˜๋„ ํฌ๊ฒŒ ์ค„์–ด๋“ญ๋‹ˆ๋‹ค.

๊ฐ€์žฅ ๊ถŒ์žฅ๋˜๋Š” ๋ฐฉ๋ฒ•์€ ์ง์ ‘ ์ž…๊ธˆ(Direct Deposit)์ž…๋‹ˆ๋‹ค. ์€ํ–‰ ๊ณ„์ขŒ๊ฐ€ ์—†๋”๋ผ๋„ ์ผ๋ถ€ ๋ชจ๋ฐ”์ผ ์•ฑ์ด๋‚˜ ์„ ๋ถˆ์นด๋“œ๊ฐ€ ๋ผ์šฐํŒ… ๋ฒˆํ˜ธ์™€ ๊ณ„์ขŒ๋ฒˆํ˜ธ๋ฅผ ์ œ๊ณตํ•œ๋‹ค๋ฉด ์ง์ ‘ ์ž…๊ธˆ์œผ๋กœ ํ™˜๊ธ‰์„ ๋ฐ›์„ ์ˆ˜ ์žˆ์Šต๋‹ˆ๋‹ค. ์‚ฌ์šฉ ์ค‘์ธ ์„œ๋น„์Šค์—์„œ ์ง€์› ์—ฌ๋ถ€๋ฅผ ๊ผญ ํ™•์ธํ•˜์„ธ์š”.


์ƒˆ๋กœ์šด IRS ๋‚ฉ๋ถ€ ๋ฐฉ์‹

๋Œ€ํ†ต๋ น ํ–‰์ •๋ช…๋ น๊ณผ ์žฌ๋ฌด๋ถ€ ์ง€์นจ์— ๋”ฐ๋ผ ์ •๋ถ€๋Š” ์ง€๊ธ‰๊ณผ ์ˆ˜๋‚ฉ ๋ชจ๋‘ ์ „์ž ๋ฐฉ์‹์œผ๋กœ ์ „ํ™˜ ์ค‘์ด๋ฉฐ, ๋ฝ๋ฐ•์Šค(์šฐํŽธ ์ˆ˜ํ‘œ ์ฒ˜๋ฆฌ)๋ฅผ ์—†์• ๊ณ  ์ „์ž ์ˆ˜๋‚ฉ์„ ํ™•๋Œ€ํ•˜๊ณ  ์žˆ์Šต๋‹ˆ๋‹ค. IRS์˜ ์šฐํŽธ ์ˆ˜ํ‘œ ๋‚ฉ๋ถ€ ๋‹จ์ผ ์ค‘๋‹จ์ผ์€ ์•„์ง ๊ณต์ง€๋˜์ง€ ์•Š์•˜์ง€๋งŒ, ์šฐํŽธ ์ˆ˜ํ‘œ ์˜์กด๋„๋ฅผ ์ค„์ด๊ณ  ์ „์ž ๋‚ฉ๋ถ€๋กœ ์ „ํ™˜ํ•˜๋Š” ๊ฒƒ์ด ์•ˆ์ „ํ•ฉ๋‹ˆ๋‹ค.

์ „์ž ๋‚ฉ๋ถ€ ๋ฐฉ๋ฒ•

  • IRS Direct Pay

    • ์€ํ–‰ ๊ณ„์ขŒ์—์„œ ์ง์ ‘ ์ด์ฒด(ACH)

    • ๊ฐœ์ธ์˜ 1040 ์‹œ๋ฆฌ์ฆˆ ์ž”์•กยท์—ฐ์žฅยท์˜ˆ๋‚ฉ์— ์ ํ•ฉ

    • ์ˆ˜์ˆ˜๋ฃŒ ์—†์Œ, ๊ฑด๋ณ„ ์˜ˆ์•ฝ ๋‚ฉ๋ถ€ ๊ฐ€๋Šฅ

  • EFTPS (Electronic Federal Tax Payment System)

    • ์‚ฌ์—…์ž ๋ฐ ์ •๊ธฐ์  ๋‚ฉ๋ถ€ยท์˜ˆ์•ฝยท๋‚ด์—ญ ๊ด€๋ฆฌ์— ์ ํ•ฉ

    • ์‚ฌ์ „ ๋“ฑ๋ก ํ•„์š” (์˜จ๋ผ์ธ ๋“ฑ๋ก ํ›„ PIN ์šฐํŽธ ์ˆ˜๋ น๊นŒ์ง€ ์•ฝ 5~7 ์˜์—…์ผ ์†Œ์š”)

    • ์—ฌ์œ  ์žˆ๊ฒŒ ๋ฏธ๋ฆฌ ๋“ฑ๋ก ๊ถŒ์žฅ

  • ์‹ ์šฉ/์ง๋ถˆ์นด๋“œยท๋””์ง€ํ„ธ ์ง€๊ฐ‘(IRS ์Šน์ธ ๊ฒฐ์ œ๋Œ€ํ–‰)

    • ๋‹จ๊ฑด ๋‚ฉ๋ถ€ ์‹œ ํŽธ๋ฆฌํ•˜๋‚˜ ์ˆ˜์ˆ˜๋ฃŒ ๋ฐœ์ƒ ๊ฐ€๋Šฅ

    • ๋‹จ, ๊ธ‰์—ฌ ์›์ฒœ์ง•์ˆ˜ ์˜ˆ์น˜(Federal Tax Deposit)๋Š” ๋ฐ˜๋“œ์‹œ EFTPS๋กœ ๋‚ฉ๋ถ€ํ•ด์•ผ ํ•จ


๋ณต์ง€๊ธ‰์—ฌ๋ฅผ ์ˆ˜ํ‘œ๋กœ ๋ฐ›๊ณ  ๊ณ„์‹  ๊ฒฝ์šฐ

์ด๋ฒˆ ์ •์ฑ…์€ IRS ํ™˜๊ธ‰๋ฟ ์•„๋‹ˆ๋ผ ๋Œ€๋ถ€๋ถ„์˜ ์—ฐ๋ฐฉ ์ •๋ถ€ ์ง€๊ธ‰์— ์ ์šฉ๋ฉ๋‹ˆ๋‹ค. ์•„์ง ์‚ฌํšŒ๋ณด์žฅ, ๋ณดํ›ˆ ๋“ฑ ๋ณต์ง€๊ธ‰์—ฌ๋ฅผ ์ข…์ด ์ˆ˜ํ‘œ๋กœ ๋ฐ›๋Š” ๋ถ„์€ GoDirect.gov์—์„œ ์ง์ ‘ ์ž…๊ธˆ์„ ์‹ ์ฒญํ•˜๊ฑฐ๋‚˜, ์žฌ๋ฌด๋ถ€ ์ „์ž ์ง€๊ธ‰ ์„ผํ„ฐ(800-967-6857)๋กœ ์ „ํ™”ํ•ด ๋“ฑ๋กํ•˜์„ธ์š”. ์€ํ–‰ ๊ณ„์ขŒ๊ฐ€ ์—†์œผ์‹  ๊ฒฝ์šฐ Direct Expressยฎ ์ง๋ถˆ์นด๋“œ๋กœ ์ˆ˜๋ นํ•  ์ˆ˜๋„ ์žˆ์Šต๋‹ˆ๋‹ค. ๋ณ€๊ฒฝ ์ ˆ์ฐจ๋Š” ๋ฐ˜๋“œ์‹œ ๊ณต์‹ ์ฑ„๋„์„ ํ†ตํ•ด ์ง„ํ–‰ํ•˜์‹œ๊ณ , ์‚ฌ์นญ ์‚ฌ๊ธฐ์— ์ฃผ์˜ํ•˜์„ธ์š”.

์ง€๊ธˆ ๋ฐ”๋กœ ์ค€๋น„ํ•ด์•ผ ํ•  ์ฒดํฌ๋ฆฌ์ŠคํŠธ

  • ํ™˜๊ธ‰ ์ˆ˜๋ น ๋ฐฉ์‹ ํ™•์ธ: ๋ผ์šฐํŒ…ยท๊ณ„์ขŒ๋ฒˆํ˜ธ๋ฅผ ์ค€๋น„ํ•˜๊ฑฐ๋‚˜, ์„ ๋ถˆ์นด๋“œ/์•ฑ์ด ์ง์ ‘ ์ž…๊ธˆ์„ ์ง€์›ํ•˜๋Š”์ง€ ํ™•์ธ

  • ๋‚ฉ๋ถ€ ๋ฐฉ์‹ ์„ ํƒ: ๊ฐ„๋‹จ ์ด์ฒด๋Š” Direct Pay, ์˜ˆ์•ฝยท์ด๋ ฅ ๊ด€๋ฆฌ๊ฐ€ ํ•„์š”ํ•˜๊ฑฐ๋‚˜ ์‚ฌ์—…์ž๋ผ๋ฉด EFTPS

  • EFTPS ์กฐ๊ธฐ ๋“ฑ๋ก: PIN ์šฐํŽธ ์ˆ˜๋ น๊นŒ์ง€ 5~7 ์˜์—…์ผ ์†Œ์š” โ†’ ์ง€๊ธˆ ๋ฐ”๋กœ ๋“ฑ๋ก

  • ์ฃผ์˜์‚ฌํ•ญ: ๊ธ‰์—ฌ ์›์ฒœ์ง•์ˆ˜ ์˜ˆ์น˜๋Š” ์นด๋“œ ๋ถˆ๊ฐ€ โ†’ EFTPS ์ด์šฉ

  • ์‚ฌ๊ธฐ ์˜ˆ๋ฐฉ: irs.gov / eftps.gov ๋“ฑ ๊ณต์‹ ์‚ฌ์ดํŠธ๋งŒ ์ด์šฉ, ์˜์‹ฌ๋˜๋Š” ์—ฐ๋ฝ์€ ์ฆ‰์‹œ ํ™•์ธ

์ž์ฃผ ๋ฌป๋Š” ์งˆ๋ฌธ(FAQ)

Q. 2025๋…„ 9์›” 30์ผ ์ดํ›„์—๋„ IRS๊ฐ€ ์šฐํŽธ ์ˆ˜ํ‘œ ๋‚ฉ๋ถ€๋ฅผ ๋ฐ›๋‚˜์š”?
A. ์žฌ๋ฌด๋ถ€๋Š” ์ „์ž ๋‚ฉ๋ถ€ ์ „ํ™˜๊ณผ ๋ฝ๋ฐ•์Šค ํ์ง€๋ฅผ ์ง€์‹œํ–ˆ์ง€๋งŒ, IRS์˜ ์ตœ์ข… ์ค‘๋‹จ์ผ์€ ์•„์ง ํ™•์ •๋˜์ง€ ์•Š์•˜์Šต๋‹ˆ๋‹ค. ์ง€๊ธˆ๋ถ€ํ„ฐ ์ „์ž ๋‚ฉ๋ถ€๋กœ ๋ฐ”๊พธ์‹œ๋Š” ๊ฒƒ์ด ์•ˆ์ „ํ•ฉ๋‹ˆ๋‹ค.

Q. ์€ํ–‰ ๊ณ„์ขŒ๊ฐ€ ์—†์–ด๋„ ํ™˜๊ธ‰์„ ๋ฐ›์„ ์ˆ˜ ์žˆ๋‚˜์š”?
A. ์ผ๋ถ€ ๋ชจ๋ฐ”์ผ ์•ฑ๊ณผ ์„ ๋ถˆ์นด๋“œ๋Š” ๋ผ์šฐํŒ…ยท๊ณ„์ขŒ๋ฒˆํ˜ธ๋ฅผ ์ œ๊ณตํ•ด ์ง์ ‘ ์ž…๊ธˆ์„ ๋ฐ›์„ ์ˆ˜ ์žˆ์Šต๋‹ˆ๋‹ค. ์‚ฌ์šฉ ์ค‘์ธ ์„œ๋น„์Šค์—์„œ ์ง€์› ์—ฌ๋ถ€๋ฅผ ํ™•์ธํ•˜์„ธ์š”.

Q. EFTPS ๋“ฑ๋ก์—๋Š” ์–ผ๋งˆ๋‚˜ ๊ฑธ๋ฆฌ๋‚˜์š”?
A. ์˜จ๋ผ์ธ ๋“ฑ๋ก ํ›„ PIN์ด ์šฐํŽธ์œผ๋กœ ๋„์ฐฉํ•˜๋Š” ๋ฐ ๋ณดํ†ต 5~7 ์˜์—…์ผ์ด ์†Œ์š”๋ฉ๋‹ˆ๋‹ค. ์ดํ›„ ํ™œ์„ฑํ™” ์ ˆ์ฐจ๋ฅผ ๊ฑฐ์ณ ๋‚ฉ๋ถ€ํ•  ์ˆ˜ ์žˆ์Šต๋‹ˆ๋‹ค.

Q. ์™œ ์ข…์ด ์ˆ˜ํ‘œ๋ฅผ ์—†์• ๋‚˜์š”?
A. ์‚ฌ๊ธฐยท์ ˆ๋„๋ฅผ ์ค„์ด๊ณ , ๋น„์šฉ์„ ์ ˆ๊ฐํ•˜๋ฉฐ, ์ง€๊ธ‰ ์†๋„๋ฅผ ๊ฐœ์„ ํ•˜๊ธฐ ์œ„ํ•œ ์ •๋ถ€ ์ฐจ์›์˜ ํ˜„๋Œ€ํ™” ์ •์ฑ…์ž…๋‹ˆ๋‹ค.

Q. ์˜ˆ์™ธ๋Š” ์—†๋‚˜์š”?
A. ๋ฒ•๋ น์ด ํ—ˆ์šฉํ•˜๋Š” ๋ฒ”์œ„์—์„œ ์ œํ•œ์  ์˜ˆ์™ธ๊ฐ€ ์กด์žฌํ•˜๋ฉฐ, ๊ตฌ์ฒด์ ์ธ ๋‚ด์šฉ์€ ์žฌ๋ฌด๋ถ€์™€ ํ•ด๋‹น ๊ธฐ๊ด€์—์„œ ์•ˆ๋‚ดํ•ฉ๋‹ˆ๋‹ค.


The 9.9% Reality: A Definitive Guide to Washington’s 2025 Capital Gains Tax and Tax-Saving Strategies

For Washington’s investors and business owners, 2025 marks a pivotal shift in the financial landscape. A new era of taxation has begun, with the state implementing a capital gains tax rate that can reach as high as 9.9% on profits from the sale of long-term assets like stocks, bonds, and business interests. This change demands more than a simple adjustment to your tax filings; it calls for a fundamental reassessment of your asset management strategy.

Legally, this tax is classified as an excise tax on the act of selling or exchanging assets, a distinction upheld by the Washington Supreme Court, rather than an income tax. The revenue generated is earmarked to fund critical state priorities, including education, early learning, and childcare programs.

The New Reality: Washington’s Two-Tier Capital Gains Tax Structure

Effective January 1, 2025, Washington’s capital gains tax moves from a single rate to a two-tiered system :

  • Tier 1 (7% Base Rate): Applies to the first $1 million of taxable capital gains (the amount of your gain after the standard deduction).
  • Tier 2 (9.9% Surtax Rate): For taxable capital gains exceeding $1 million, a 2.9% surtax is added, bringing the total marginal rate to 9.9%.

A standard deduction, which is adjusted annually for inflation, is available to all filers. For 2024, this deduction was $270,000. Crucially, the $1 million threshold for the higher surtax is not indexed for inflation, meaning that over time, more taxpayers will likely find their gains falling into the higher bracket.

For example, if you realize a $1,500,000 taxable gain in 2025 (resulting in a $1,230,000 gain after the $270,000 deduction), your total tax liability would be $92,770. This is $6,670 more than under the previous 7% flat-rate system. The tax impact grows exponentially with the size of the gain.  

The Critical Question: What Is Exempt from the Tax?

Fortunately, the tax does not apply to all asset sales. The Washington State law (RCW 82.87) provides several key exemptions:

  • Real Estate: All gains from the sale of real estateโ€”including commercial buildings, land, and rental propertiesโ€”are fully exempt from Washington’s capital gains tax. When selling an interest in an entity that owns real estate, the exemption applies only to the portion of the gain directly attributable to the property’s value, making an accurate appraisal essential.
  • Qualified Family-Owned Small Businesses (QFOSB): Gains from the sale of a qualifying small business may be deductible. The primary requirements include:

    • The business must have worldwide gross revenue below a certain threshold ($10,790,000 for 2024) in the 12 months preceding the sale.
    • The taxpayer or their family members must have owned the business for at least five years and “materially participated” in its operation for at least five of the ten years before the sale.
    • Retirement Accounts: Capital gains realized within federally qualified retirement accounts, such as 401(k)s, IRAs, and Roth IRAs, are not subject to the tax.

    Advanced Tax-Saving Strategies: Beyond Simple Timing

    Effective tax planning requires a sophisticated approach based on a clear understanding of state law. Some widely known federal strategies may not apply in Washington, creating potential pitfalls for the uninformed.
     

    Strategies Requiring Caution

    • Qualified Opportunity Funds (QOFs): While the federal government offers significant tax deferrals for investing capital gains in QOFs, Washington State does not recognize this benefit. Even if you reinvest your gains into a QOF, you must still pay the Washington capital gains tax in the year the gain was realized.
    • Federal SALT Deduction: Attempting to deduct your Washington capital gains tax payment on your federal return is unlikely to succeed. The tax’s classification as an “excise tax” likely makes it ineligible for the State and Local Tax (SALT) deduction, which is primarily for income, sales, and property taxes. Furthermore, the federal SALT deduction is capped (at $10,000, though temporarily raised to $40,000 for 2025 with phase-outs for high earners), limiting its utility for those with significant tax liabilities.

    Effective Strategies for Washington

    • Qualified Small Business Stock (QSBS): This remains one of the most powerful tax-saving tools. Washington’s tax calculation begins with your federal net long-term capital gain. Under federal law (IRC ยง1202), gains from the sale of QSBS held for over five years can be excluded from federal tax. Because it is excluded at the federal level, the gain is also automatically exempt from Washington’s capital gains tax. This provides a strong incentive for founders and early-stage investors to structure their businesses as C-Corporations.
    • Installment Sales: Structuring the sale of an asset to receive payments over several years allows you to spread the recognition of the gain. This can help keep your annual gain below the $1 million surtax threshold, or even below the standard deduction, thereby reducing or eliminating your tax liability.
    • Change of Domicile: For intangible assets like stocks and bonds, the tax is based on the seller’s domicile at the time of the sale. Legally establishing residency in a state with no capital gains tax (such as Nevada or Texas) before a major liquidity event is a valid strategy. However, this requires a genuine relocation, substantiated by clear evidence like a new driver’s license, voter registration, and primary home, as the state will scrutinize such moves closely.

    Proactive Design, Not Post-Sale Reaction

    Washington’s new capital gains tax structure presents a complex but navigable challenge. The key to preserving your wealth lies not in last-minute maneuvers but in proactive, informed planning. The law itself, particularly the robust exemptions for real estate and qualified small businesses, offers the most reliable paths to tax efficiency. Before signing any major asset sale agreement, it is imperative to consult with a tax professional. A well-designed strategy, tailored to your specific circumstances and grounded in a thorough understanding of Washington’s tax code, can save you tens or even hundreds of thousands of dollars. In the 9.9% era, successful asset management begins long before the sale is final.

    Related services from Alisa Na CPAs & Advisors

2025๋…„ 3๋ถ„๊ธฐ ์›Œ์‹ฑํ„ด์ฃผ ํŒ๋งค์„ธ์œจ ๋ณ€๊ฒฝ

์•ˆ๋…•ํ•˜์„ธ์š”.

2025๋…„ ํ•˜๋ฐ˜๊ธฐ๋ถ€ํ„ฐ ์‹œํ–‰๋˜๋Š” ์›Œ์‹ฑํ„ด์ฃผ Department of Revenue์˜ ์„ธ๋ฒ• ๊ฐœ์ •๊ณผ ๊ด€๋ จํ•˜์—ฌ, ๊ณ ๊ฐ๋‹˜์˜ ๋น„์ฆˆ๋‹ˆ์Šค์— ์˜ํ–ฅ์„ ์ค„ ์ˆ˜ ์žˆ๋Š” ๋‘ ๊ฐ€์ง€ ์ฃผ์š” ๋ณ€๊ฒฝ ์‚ฌํ•ญ์„ ์•ˆ๋‚ด๋“œ๋ฆฝ๋‹ˆ๋‹ค. ํ•ด๋‹น ๋‚ด์šฉ์€ ์‚ฌ์ „์— ํ™•์ธํ•˜๊ณ  ์ค€๋น„ํ•˜์‹œ๋Š” ๊ฒƒ์ด ์ค‘์š”ํ•ฉ๋‹ˆ๋‹ค.

์‹ ๊ทœ ์„œ๋น„์Šค์— ๋Œ€ํ•œ ํŒ๋งค์„ธ ์ ์šฉ โ€“ 2025๋…„ 10์›” 1์ผ ์‹œํ–‰

ESSB 5814 ๋ฒ•์•ˆ์— ๋”ฐ๋ผ, ์›Œ์‹ฑํ„ด์ฃผ๋Š” โ€˜์†Œ๋งค ํŒ๋งค(retail sales)โ€™์˜ ์ •์˜๋ฅผ ํ™•๋Œ€ํ•˜์˜€์Šต๋‹ˆ๋‹ค.

2025๋…„ 10์›” 1์ผ๋ถ€ํ„ฐ, ๋‹ค์Œ๊ณผ ๊ฐ™์€ ์„œ๋น„์Šค๊ฐ€ ํŒ๋งค์„ธ(Sales Tax) ๊ณผ์„ธ ๋Œ€์ƒ์— ํฌํ•จ๋ฉ๋‹ˆ๋‹ค:

  • ์ •๋ณด๊ธฐ์ˆ (IT) ์„œ๋น„์Šค
  • ๋งž์ถคํ˜• ์›น์‚ฌ์ดํŠธ ๊ฐœ๋ฐœ
  • ์กฐ์‚ฌ, ๋ณด์•ˆ, ํ˜„๊ธˆ ์ˆ˜์†ก ์„œ๋น„์Šค
  • ์ž„์‹œ ์ธ๋ ฅ ํŒŒ๊ฒฌ
  • ๊ด‘๊ณ  ์„œ๋น„์Šค
  • ๋ผ์ด๋ธŒ ํ”„๋ ˆ์  ํ…Œ์ด์…˜
  • ๋งž์ถคํ˜• ์†Œํ”„ํŠธ์›จ์–ด ๋ฐ ์†Œํ”„ํŠธ์›จ์–ด ์ปค์Šคํ„ฐ๋งˆ์ด์ง•
  • ์ผ๋ถ€ ๋””์ง€ํ„ธ ์ž๋™ํ™” ์„œ๋น„์Šค((Digital Automated Services, DAS)

์ด๋Ÿฌํ•œ ๋ณ€๊ฒฝ์€ ๊ด€๋ จ ์„œ๋น„์Šค๋ฅผ ์ œ๊ณตํ•˜๊ฑฐ๋‚˜ ๊ตฌ๋งคํ•˜๋Š” ์‚ฌ์—…์ž ๋ชจ๋‘์—๊ฒŒ ์˜ํ–ฅ์„ ๋ฏธ์น  ์ˆ˜ ์žˆ์œผ๋ฏ€๋กœ, ์„ธ๊ธˆ ๋ถ€๊ณผ ์—ฌ๋ถ€๋ฅผ ์‚ฌ์ „์— ๊ฒ€ํ† ํ•˜์‹œ๊ณ  ๊ณผ์„ธ ๋ฐฉ์‹ ๋ณ€๊ฒฝ์— ๋Œ€๋น„ํ•˜์—ฌ ๋ฏธ๋ฆฌ ์ค€๋น„ํ•˜์‹ค ๊ฒƒ์„ ๊ถŒ์žฅ๋“œ๋ฆฝ๋‹ˆ๋‹ค.

์›Œ์‹ฑํ„ด์ฃผ Department of Revenue ์€ ํ•ด๋‹น ๋ณ€๊ฒฝ ์‚ฌํ•ญ๊ณผ ๊ด€๋ จํ•˜์—ฌ ํ–ฅํ›„ ๋ช‡ ๊ฐœ์›” ๋‚ด์— ๋ณด๋‹ค ๊ตฌ์ฒด์ ์ธ ์ง€์นจ ๋ฐ ์˜ˆ์™ธ์‚ฌํ•ญ ๋“ฑ์„ ๋ฐœํ‘œํ•  ์˜ˆ์ •์ž…๋‹ˆ๋‹ค.
https://dor.wa.gov/taxes-rates/retail-sales-tax/services-newly-subject-retail-sales-tax

ํ˜„์žฌ๋Š” ์•„๋ž˜ ๋งํฌ์—์„œ ๊ณต์‹ **์ž์ฃผ ๋ฌป๋Š” ์งˆ๋ฌธ(FAQ)**์„ ํ™•์ธํ•˜์‹ค ์ˆ˜ ์žˆ์Šต๋‹ˆ๋‹ค:
ESSB 5814 โ€“ ์ž์ฃผ ๋ฌป๋Š” ์งˆ๋ฌธ ๋ณด๊ธฐ

2025๋…„ 2๋ถ„๊ธฐ ์—…๋ฐ์ดํŠธ


2025 Quarter 3: Washington State Sales Tax Rate Changes

Dear Clients,

We want to bring your attention to two important updates from the Washington State Department of Revenue that may affect your business operations later this year.

New Services Subject to Sales Tax โ€“ Effective October 1, 2025

Under Engrossed Substitute Senate Bill (ESSB) 5814, Washington State is expanding the definition of โ€œretail sales.โ€

Starting October 1, 2025, the following services will be subject to retail sales tax:

  • Information technology services
  • Custom website development
  • Investigation, security, and armored car services
  • Temporary staffing
  • Advertising services
  • Live presentations
  • Custom software and software customization
  • Certain digital automated services (DAS)

Additional Guidance

The Department of Revenue will release more details in the coming months.

https://dor.wa.gov/taxes-rates/retail-sales-tax/services-newly-subject-retail-sales-tax

For now, you can review the Frequently Asked Questions on DORโ€™s website here:

FAQ โ€“ ESSB 5814

If you provide or purchase any of these services, we recommend preparing now for the upcoming changes in how these transactions will be taxed.

Quarter Two Updates


2025-08-07 ์›Œ์‹ฑํ„ด์ฃผ ์„ธ๊ธˆ ์—…๋ฐ์ดํŠธ: ์‹ ๊ทœ ํŒ๋งค์„ธ ๊ทœ์ • ๋ฐ ํˆฌ์ž์†Œ๋“ ์ž์ง„์‹ ๊ณ  ํ”„๋กœ๊ทธ๋žจ ์•ˆ๋‚ด

์•ˆ๋…•ํ•˜์„ธ์š”.

2025๋…„ ํ•˜๋ฐ˜๊ธฐ๋ถ€ํ„ฐ ์‹œํ–‰๋˜๋Š” ์›Œ์‹ฑํ„ด์ฃผ Department of Revenue์˜ ์„ธ๋ฒ• ๊ฐœ์ •๊ณผ ๊ด€๋ จํ•˜์—ฌ, ๊ณ ๊ฐ๋‹˜์˜ ๋น„์ฆˆ๋‹ˆ์Šค์— ์˜ํ–ฅ์„ ์ค„ ์ˆ˜ ์žˆ๋Š” ๋‘ ๊ฐ€์ง€ ์ฃผ์š” ๋ณ€๊ฒฝ ์‚ฌํ•ญ์„ ์•ˆ๋‚ด๋“œ๋ฆฝ๋‹ˆ๋‹ค. ํ•ด๋‹น ๋‚ด์šฉ์€ ์‚ฌ์ „์— ํ™•์ธํ•˜๊ณ  ์ค€๋น„ํ•˜์‹œ๋Š” ๊ฒƒ์ด ์ค‘์š”ํ•ฉ๋‹ˆ๋‹ค.

์‹ ๊ทœ ์„œ๋น„์Šค์— ๋Œ€ํ•œ ํŒ๋งค์„ธ ์ ์šฉ โ€“ 2025๋…„ 10์›” 1์ผ ์‹œํ–‰

ESSB 5814 ๋ฒ•์•ˆ์— ๋”ฐ๋ผ, ์›Œ์‹ฑํ„ด์ฃผ๋Š” โ€˜์†Œ๋งค ํŒ๋งค(retail sales)โ€™์˜ ์ •์˜๋ฅผ ํ™•๋Œ€ํ•˜์˜€์Šต๋‹ˆ๋‹ค.

2025๋…„ 10์›” 1์ผ๋ถ€ํ„ฐ, ๋‹ค์Œ๊ณผ ๊ฐ™์€ ์„œ๋น„์Šค๊ฐ€ ํŒ๋งค์„ธ(Sales Tax) ๊ณผ์„ธ ๋Œ€์ƒ์— ํฌํ•จ๋ฉ๋‹ˆ๋‹ค:

  • ์ •๋ณด๊ธฐ์ˆ (IT) ์„œ๋น„์Šค
  • ๋งž์ถคํ˜• ์›น์‚ฌ์ดํŠธ ๊ฐœ๋ฐœ
  • ์กฐ์‚ฌ, ๋ณด์•ˆ, ํ˜„๊ธˆ ์ˆ˜์†ก ์„œ๋น„์Šค
  • ์ž„์‹œ ์ธ๋ ฅ ํŒŒ๊ฒฌ
  • ๊ด‘๊ณ  ์„œ๋น„์Šค
  • ๋ผ์ด๋ธŒ ํ”„๋ ˆ์  ํ…Œ์ด์…˜
  • ๋งž์ถคํ˜• ์†Œํ”„ํŠธ์›จ์–ด ๋ฐ ์†Œํ”„ํŠธ์›จ์–ด ์ปค์Šคํ„ฐ๋งˆ์ด์ง•
  • ์ผ๋ถ€ ๋””์ง€ํ„ธ ์ž๋™ํ™” ์„œ๋น„์Šค((Digital Automated Services, DAS)

์ด๋Ÿฌํ•œ ๋ณ€๊ฒฝ์€ ๊ด€๋ จ ์„œ๋น„์Šค๋ฅผ ์ œ๊ณตํ•˜๊ฑฐ๋‚˜ ๊ตฌ๋งคํ•˜๋Š” ์‚ฌ์—…์ž ๋ชจ๋‘์—๊ฒŒ ์˜ํ–ฅ์„ ๋ฏธ์น  ์ˆ˜ ์žˆ์œผ๋ฏ€๋กœ, ์„ธ๊ธˆ ๋ถ€๊ณผ ์—ฌ๋ถ€๋ฅผ ์‚ฌ์ „์— ๊ฒ€ํ† ํ•˜์‹œ๊ณ  ๊ณผ์„ธ ๋ฐฉ์‹ ๋ณ€๊ฒฝ์— ๋Œ€๋น„ํ•˜์—ฌ ๋ฏธ๋ฆฌ ์ค€๋น„ํ•˜์‹ค ๊ฒƒ์„ ๊ถŒ์žฅ๋“œ๋ฆฝ๋‹ˆ๋‹ค.

์›Œ์‹ฑํ„ด์ฃผ Department of Revenue ์€ ํ•ด๋‹น ๋ณ€๊ฒฝ ์‚ฌํ•ญ๊ณผ ๊ด€๋ จํ•˜์—ฌ ํ–ฅํ›„ ๋ช‡ ๊ฐœ์›” ๋‚ด์— ๋ณด๋‹ค ๊ตฌ์ฒด์ ์ธ ์ง€์นจ ๋ฐ ์˜ˆ์™ธ์‚ฌํ•ญ ๋“ฑ์„ ๋ฐœํ‘œํ•  ์˜ˆ์ •์ž…๋‹ˆ๋‹ค.
https://dor.wa.gov/taxes-rates/retail-sales-tax/services-newly-subject-retail-sales-tax

ํ˜„์žฌ๋Š” ์•„๋ž˜ ๋งํฌ์—์„œ ๊ณต์‹ **์ž์ฃผ ๋ฌป๋Š” ์งˆ๋ฌธ(FAQ)**์„ ํ™•์ธํ•˜์‹ค ์ˆ˜ ์žˆ์Šต๋‹ˆ๋‹ค:
ESSB 5814 โ€“ ์ž์ฃผ ๋ฌป๋Š” ์งˆ๋ฌธ ๋ณด๊ธฐ

ํˆฌ์ž์†Œ๋“ ์ž์ง„์‹ ๊ณ  ํ”„๋กœ๊ทธ๋žจ โ€“ 2025๋…„ 7์›” 1์ผ๋ถ€ํ„ฐ ์‹œํ–‰

ESSB 5167 ๋ฒ•์•ˆ์— ๋”ฐ๋ผ, ์‚ฌ์—… ๋ฐ ์ง์—…์„ธ(Business & Occupation Tax) ๋Œ€์ƒ์ธ ์‹ ๊ณ ๋˜์ง€ ์•Š์€ ํˆฌ์ž์†Œ๋“์„ ๋ณด์œ ํ•œ ์‚ฌ์—…์ž๋ฅผ ์œ„ํ•œ ํ•œ์‹œ์  ์ž์ง„์‹ ๊ณ  ํ”„๋กœ๊ทธ๋žจ์ด ์‹œํ–‰ ์ค‘์ž…๋‹ˆ๋‹ค.

์ฃผ์š” ๋‚ด์šฉ:

  • ์ž๊ฒฉ ์š”๊ฑด์„ ์ถฉ์กฑํ•œ ์‚ฌ์—…์ž๋Š” ์ตœ๋Œ€ 5๋…„ ์ „๊นŒ์ง€ ์†Œ๊ธ‰ํ•˜์—ฌ ํˆฌ์ž์†Œ๋“์„ ์‹ ๊ณ ํ•  ์ˆ˜ ์žˆ์Šต๋‹ˆ๋‹ค.
  • ์‚ฌ์—…์˜ ์ฃผ๋œ ๋ชฉ์ ์ด ํˆฌ์ž๊ฐ€ ์•„๋‹Œ ๊ฒฝ์šฐ, ํˆฌ์ž์†Œ๋“์€ ์ด์ˆ˜์ž…(gross receipts)์˜ 5%๊นŒ์ง€ Safe Harbor ํ•œ๋„ ๋‚ด ๊ณต์ œ๊ฐ€ ๊ฐ€๋Šฅํ•ฉ๋‹ˆ๋‹ค.
  • ์ด๋ฏธ ์ง•์ˆ˜๋˜์—ˆ์œผ๋‚˜ ์‹ ๊ณ ๋˜์ง€ ์•Š์€ ํŒ๋งค์„ธ์— ๋Œ€ํ•ด์„œ๋Š” ๊ฐ€์‚ฐ์„ธ๋Š” ๋ถ€๊ณผ๋˜๋ฉฐ, ์ด์ž ๋ฐ ์ผ๋ถ€ ๋ฒŒ๊ธˆ์€ ๋ฉด์ œ๋ฉ๋‹ˆ๋‹ค
  • ๋ณธ ํ”„๋กœ๊ทธ๋žจ์€ ์ผ์ • ๊ธฐ๊ฐ„ ๋™์•ˆ๋งŒ ์ œ๊ณต๋˜๋ฉฐ, ์ž์ง„์‹ ๊ณ ๋ฅผ ํ†ตํ•ด ์ด์ž ๋ฐ ์ผ๋ถ€ ๋ฒŒ๊ธˆ์˜ ๋ฉด์ œ๋ฅผ ๋ฐ›์„ ์ˆ˜ ์žˆ๋Š” ๊ธฐํšŒ์ž…๋‹ˆ๋‹ค. ๋ˆ„๋ฝ๋œ ํˆฌ์ž์†Œ๋“์ด ์žˆ์œผ์‹œ๋‹ค๋ฉด, ์ด๋ฒˆ ๊ธฐํšŒ๋ฅผ ํ™œ์šฉํ•˜์—ฌ ์‹ ๊ณ ๋ฅผ ์™„๋ฃŒํ•˜์‹ค์ˆ˜ ์žˆ์Šต๋‹ˆ๋‹ค.

๊ณ ๊ฐ๋‹˜์˜ ์‚ฌ์—…์ด ๋ณธ ํ”„๋กœ๊ทธ๋žจ์˜ ๋Œ€์ƒ์— ํ•ด๋‹น๋˜๋Š”์ง€, ๊ทธ๋ฆฌ๊ณ  ์‹ ๊ณ ๋˜์ง€ ์•Š์€ ํˆฌ์ž์†Œ๋“์ด ์žˆ๋Š”์ง€๋ฅผ ์‚ฌ์ „์— ๊ฒ€ํ† ํ•˜์‹œ๊ธธ ๊ถŒ์žฅ๋“œ๋ฆฝ๋‹ˆ๋‹ค.


ํ•ด๋‹น ๋ณ€๊ฒฝ ์‚ฌํ•ญ์„ ์‚ฌ์ „์— ํ™•์ธํ•˜๊ณ  ์ค€๋น„ํ•˜์‹œ๋Š” ๊ฒƒ์ด ์ค‘์š”ํ•ฉ๋‹ˆ๋‹ค. ๋‚ด์šฉ์„ ์‚ดํŽด๋ณด์‹  ํ›„ ๊ถ๊ธˆํ•œ ์ ์ด ์žˆ์œผ์‹œ๋ฉด ์–ธ์ œ๋“ ์ง€ ๋ฌธ์˜ํ•ด์ฃผ์‹œ๊ธฐ ๋ฐ”๋ž๋‹ˆ๋‹ค. ์ €ํฌ ํŒ€์ด ์„ฑ์‹คํžˆ ๋„์™€๋“œ๋ฆฌ๊ฒ ์Šต๋‹ˆ๋‹ค.
๊ฐ์‚ฌํ•ฉ๋‹ˆ๋‹ค.

Alisa Na CPAs & Advisors